← Back to Mike's Thoughts
Mike Smith
September 13, 2026

Welcome to Teaching Sustainability, the 20-week series from Aclymate created to help small and mid-sized business leaders understand what sustainability means, why it matters, and what to do next. Each week, we cover one practical topic, from carbon accounting and reporting to certifications and climate action, in clear, simple language designed to help you build a more resilient, credible, and competitive business.
Last chapter, we covered science-based targets and what it means to set a reduction goal that holds up under scrutiny. This chapter shifts from what you commit to internally to what the outside world may require—or increasingly expect—from your business.
Climate and sustainability reporting requirements are expanding in many markets, even as some rules are being narrowed, delayed, or challenged. For small and mid-sized businesses, the most important point is not simply whether your company is directly regulated. It is whether your customers, suppliers, lenders, investors, or business partners are—and what information they may eventually need from you.
For most of the past two decades, corporate climate disclosure was largely voluntary. Companies measured and reported emissions because investors, customers, employees, or leadership teams wanted the information.
That has changed.
Governments in California, the European Union, Australia, the United Kingdom, and elsewhere have introduced climate and sustainability reporting frameworks. At the same time, some requirements have been scaled back or challenged. The U.S. Securities and Exchange Commission's climate disclosure rule is a good example: it was adopted in 2024, stayed during litigation, and in May 2026 the SEC proposed rescinding it entirely.
So the story isn't simply that every regulation is becoming stricter. The more important trend is that measuring emissions, understanding climate risk, and producing credible sustainability information are becoming normal parts of doing business with large organizations.
And because large organizations rely on thousands of smaller suppliers, those expectations can travel down the supply chain.
The result is a global reporting landscape increasingly built around common ideas: understanding climate risk, measuring greenhouse gas emissions, reporting credible data, and using recognized frameworks such as the GHG Protocol and ISSB standards.
There is another important force SMB leaders should understand: the Science Based Targets initiative, or SBTi.
SBTi is not a government regulator. Companies voluntarily use it to set emissions-reduction and Net Zero targets aligned with climate science.
But a voluntary commitment made by your customer can still create a requirement for you.
For many companies with significant Scope 3 emissions, SBTi requires targets that address the value chain. Under the current framework, supplier-engagement targets and emissions-reduction targets can be used to cover significant portions of Scope 3 emissions. That gives large companies a strong reason to engage their suppliers, request emissions information, and encourage them to measure and reduce their own footprints.
SBTi published Version 2.0 of its Corporate Net-Zero Standard in June 2026. Target validation using Version 2.0 begins in 2027, with a transition period before it becomes the required standard for new submissions. The framework puts greater emphasis on implementation, value-chain action, and demonstrating progress.
For an SMB, the practical question is simple:
Do any of your largest customers have an SBTi target?
If they do, you may eventually become part of how they achieve it.
This is the part many small and mid-sized business leaders miss.
If your company falls below the revenue or employee thresholds in these regulations, you may assume none of this applies to you.
Directly, that may be true.
Commercially, it may not be.
As we've covered throughout this series, Scope 3 captures emissions across a company's value chain—including purchased products, materials, transportation, business travel, and suppliers.
When a large company is required to understand or disclose Scope 3 emissions—or has voluntarily committed to reducing them—it needs better information about its supply chain.
That can create requests for information from suppliers.
Those requests may appear as:
The regulation or climate commitment may technically belong to your customer, but part of the work can still land on your desk.
That's why having a repeatable approach to carbon accounting and Scope 1, 2, and 3 emissions measurement is becoming increasingly valuable even for companies that aren't directly subject to climate disclosure laws.
Banks, insurers, investors, and other financial institutions are also paying greater attention to climate-related risks and sustainability performance.
In some markets this is regulatory. In others it is simply part of risk management.
Over time, lenders may ask more questions about energy use, climate exposure, supply-chain risks, emissions, or environmental practices as part of financing decisions.
The important lesson is the same: you don't need to be directly regulated for sustainability information to become relevant to your business relationships.
Reporting isn't the only area changing. Governments are also paying closer attention to what companies say about sustainability.
The European Union has already adopted its Directive on Empowering Consumers for the Green Transition. The new rules begin applying on September 27, 2026, and strengthen protections against misleading environmental claims. Among other things, they restrict vague environmental claims such as calling something "green" or "environmentally friendly" without adequate substantiation and impose new restrictions on certain claims based on carbon offsetting.
The separate EU Green Claims Directive, which would establish additional requirements for substantiating explicit environmental claims, remains a legislative proposal and should not yet be described as an enacted requirement.
In the United States, the Federal Trade Commission's Green Guides for environmental marketing claims warn companies against broad, unqualified claims such as "green" and "eco-friendly" because they can be difficult or impossible to substantiate. Environmental claims should be supported by competent and reliable evidence and clearly explain the specific environmental benefit being claimed.
The practical implication is straightforward:
If you make a sustainability claim, you should be able to show the data behind it.
Claims such as "sustainable," "carbon neutral," "climate friendly," "Net Zero," or "eco-friendly" should not exist only in marketing copy. They should connect to documented methodology, measurable actions, and credible evidence.
Aclymate is built to help companies create the organized emissions data and sustainability information increasingly requested by customers, reporting frameworks, certifications, and other stakeholders.
The platform helps companies calculate and manage Scope 1, Scope 2, and Scope 3 emissions, maintain supporting data and methodology, prepare sustainability reporting, respond to customer requests, and manage certifications and sustainability programs.
And because most small and mid-sized companies don't have a large sustainability department, Aclymate combines software with expert support.
With Aclymate One, Carbon Bookkeepers and Sustainability Consultants can help collect and organize data, maintain your carbon accounting, prepare reports, respond to sustainability requests, support certifications, and help determine which requirements actually matter to your business.
In other words, you don't need to become an expert in SB 253, CSRD, SBTi, CDP, EcoVadis, the GHG Protocol, and every new sustainability acronym.
You need a system—and a team—that helps you stay ready.
Climate regulation is no longer simply a large-company issue.
Some rules have expanded. Others have been narrowed, delayed, challenged, or reconsidered. But underneath those regulatory changes, something bigger is happening: sustainability information is becoming part of how companies evaluate suppliers, manage risk, set climate targets, report to stakeholders, and protect their brands.
For SMBs, that's the real issue.
The requirement may come from California. It may come from Europe. It may come from an SBTi commitment, an EcoVadis assessment, a CDP questionnaire, an RFP, a lender, or simply one of your biggest customers.
The businesses that already know their numbers, maintain good documentation, and can respond with credible information will handle those requests much more easily.
The ones that don't may find themselves scrambling to meet someone else's deadline.
You may not be regulated today. But being sustainability-ready is increasingly becoming part of being business-ready.
Want to understand where your company stands? Start with Aclymate or talk with a sustainability expert about your carbon accounting, reporting, certification, and customer requirements.
Get Aclymate's practical sustainability content delivered weekly.

Most small and mid-sized businesses know they should be doing something about sustainability. The ones that actually make progress share one thing in common: they started with a clear sequence. Here it is.
Read Article
SBTi requirements are reshaping supply chains. Learn what science-based targets mean for carbon accounting, reporting, suppliers, and mid-sized companies.
Read Article
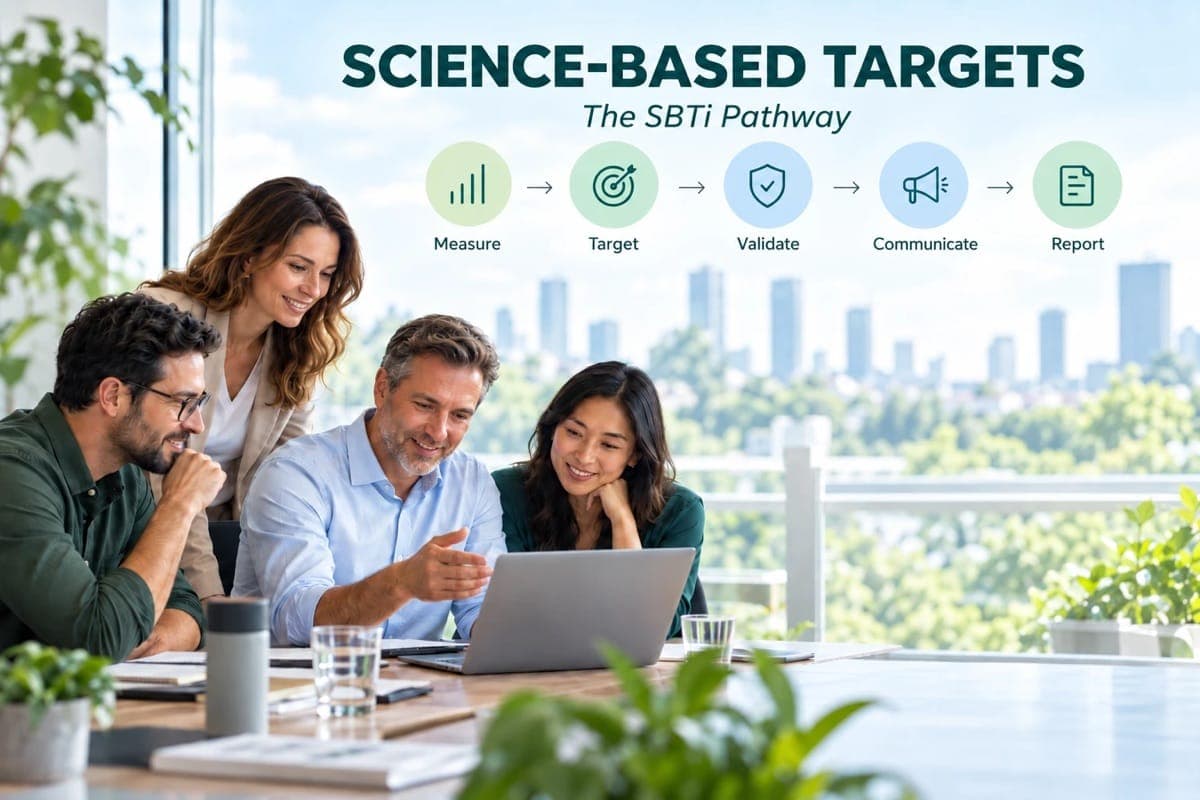
From carbon accounting to validation and annual reporting, here's what companies should expect before committing to SBTi.
Read Article
Talk with a Sustainability Expert, see a demo, or start free to put the Aclymate platform and experts to work for your team.